

Commercial credit requires judgment, but financial preparation should not require reinvention on every deal. When analysts use different spreadsheet structures, classification methods, or preparation habits, variation enters the credit process before meaningful analysis begins.
The issue isn’t necessarily that one approach is wrong. It’s that reviewers may struggle to distinguish between differences in borrower financials, intentional analyst adjustments, and variations in how the spread was prepared. That creates process risk.
The goal of standardized financial spreading is not to remove analyst discretion. Credit professionals still need to understand borrower circumstances, investigate exceptions, challenge assumptions, and apply judgment. The opportunity is to standardize the repeatable work that happens before those decisions are made, so professional judgment becomes easier to identify and review.
Key Takeaways
- Financial spreading can introduce process risk when preparation varies across analysts, teams, or deals.
- Standardization creates a common baseline without requiring every borrower to be treated identically.
- A consistent baseline gives reviewers a clearer reference point for investigating exceptions and intentional deviations.
- Credit judgment should remain with experienced professionals, while repeatable preparation should rely less on individual spreadsheet habits.
- FlashSpread helps lenders prepare borrower financial information in standardized financial spreads before credit analysis.
Process Risk Begins Before Credit Analysis
Manual spreading processes often evolve around the people using them. An experienced analyst builds a spreadsheet that works well. Another team modifies it for a different borrower type. A branch develops its own version. Over time, similar financial information may be categorized, presented, or adjusted differently depending on who prepared the file.
The challenge is not simply inconsistency in appearance. When a spread moves to another analyst, manager, or credit committee, the reviewer may first need to understand how the preparer approached the financials before focusing on what the borrower’s performance actually means.
That becomes more important when two spreads differ for reasons that are not obvious. A line item may be treated differently because the borrower is unusual. An analyst may have made a deliberate adjustment based on credit policy or borrower context. Or the difference may exist simply because two analysts use different preparation methods. Without a consistent baseline, those explanations are harder to separate.
Standardization Makes Exceptions Visible
Standardization becomes valuable when it helps distinguish normal preparation from something that genuinely deserves attention. A standardized process establishes what the expected financial structure should look like. Once that baseline exists, a deviation carries more meaning.
Consider an analyst adjusting for a significant one-time expense. Without a consistent spreading structure, another reviewer may struggle to determine whether the adjustment reflects an intentional credit decision or an individual preparation method. Standardization provides a common reference point, making the adjustment easier to identify, document, and evaluate.
The same principle applies to unusual classifications, reporting periods, ownership structures, or borrower-specific adjustments. Standardization removes one source of ambiguity: variation created by the preparation process itself.
That gives credit leaders a stronger governance signal. Once the baseline is consistent, deviation itself becomes information. Reviewers can spend more time understanding why something changed instead of first determining whether the difference came from the borrower or the spreadsheet.
Standardize the Baseline, Not the Judgment
A strong spreading process should be clear about what needs consistency and what should remain judgment-based. Routine preparation can follow a common structure, with consistent approaches to organizing financial information, presenting reporting periods, handling common line items, and preparing borrower financials for review.
Borrower interpretation is different. An unusual business model, one-time event, changing revenue pattern, or complex ownership structure may require an analyst to depart from the standard approach and explain why. That flexibility should remain because standardization should make judgment calls more visible, not eliminate them.
A repeatable preparation process gives analysts a consistent starting point while preserving their responsibility to investigate exceptions, document adjustments, and apply institutional credit standards.
Subscribe to BeSmartee 's Digital Mortgage Blog to receive:
- Mortgage Industry Insights
- Security & Compliance Updates
- Q&A's Featuring Mortgage & Technology Experts
Institutions should depend on experienced professionals for judgment. They should not have to depend on individual spreadsheet habits for consistency.
Why Standardization Matters More as Credit Teams Grow
Individual working styles are easier to manage when a small group of experienced analysts works closely together. The challenge grows as lending volume increases, analysts join or leave, responsibilities move between teams, or multiple branches handle commercial credit. What once lived in shared experience can become difficult to transfer across the organization.
A standardized spreading process creates a common operating foundation. Reviewers become familiar with how financial information will be presented, work can move between analysts with less dependence on personal spreadsheet conventions, and new employees can learn an established preparation approach rather than inheriting several different ones.
From a credit risk management perspective, a consistent process also improves management visibility. When leaders know what the normal process should look like, they can focus more directly on intentional adjustments, unusual borrower circumstances, and the reasoning behind a recommendation.
That is where standardization supports scale. It makes the institution less dependent on individual preparation methods without making the credit process rigid.
Where FlashSpread Fits
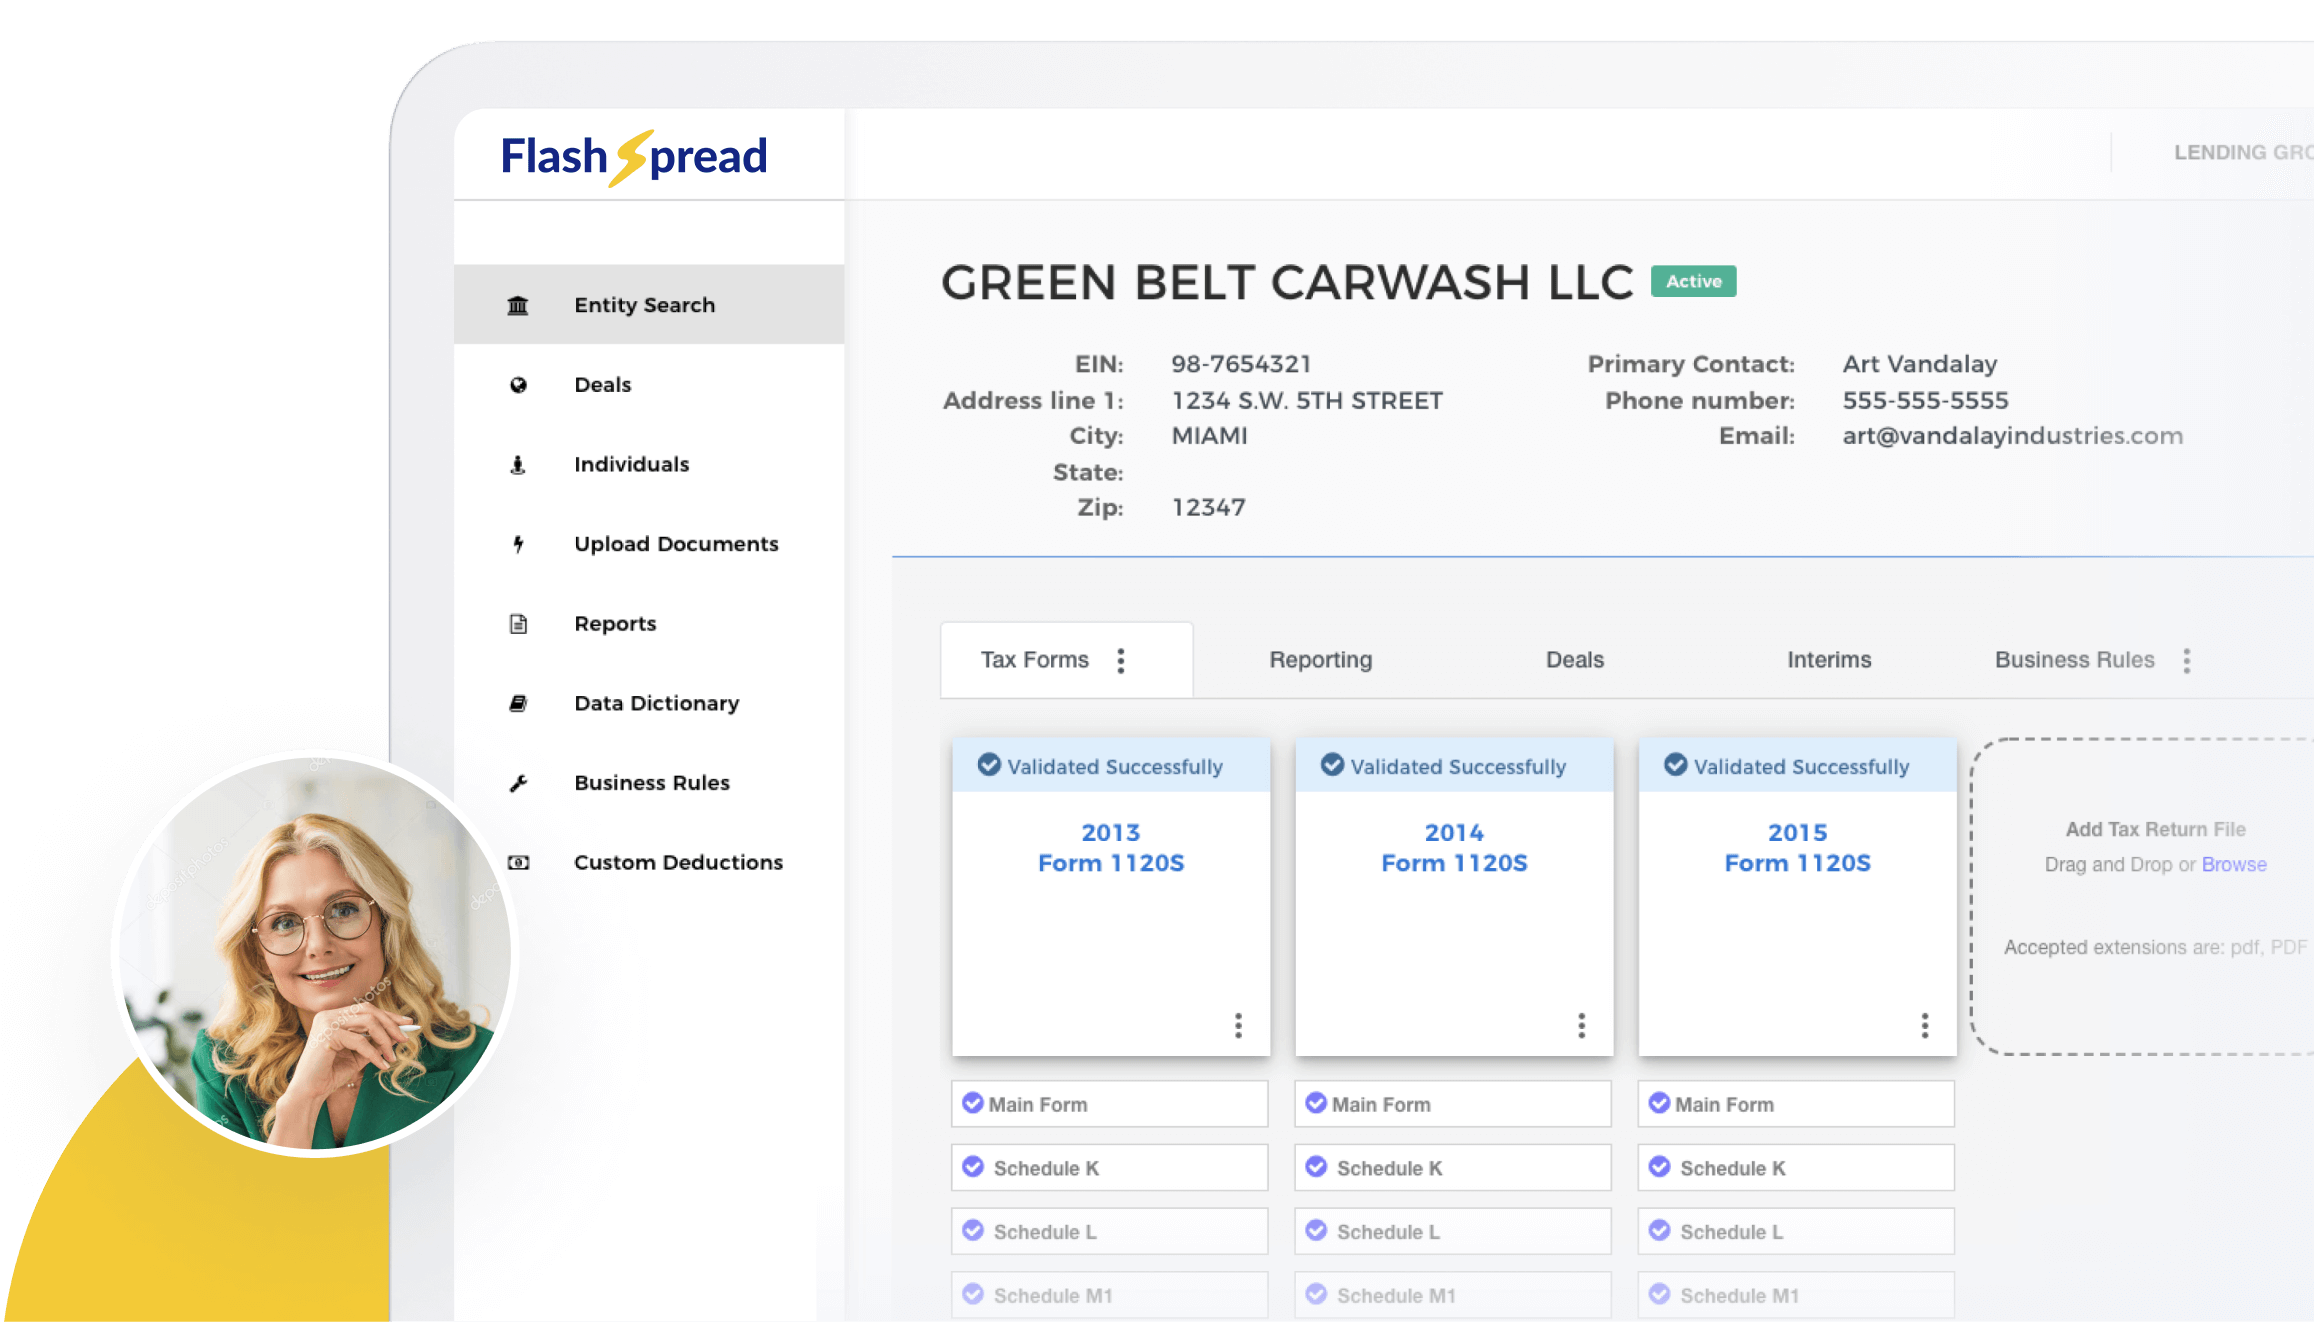
FlashSpread supports automated financial spreading by extracting financial information from borrower documents and organizing it into standardized financial spreads. For lenders evaluating financial spreading software, the business value is not simply faster preparation. It is a more consistent process leading into commercial credit analysis, while interpretation and lending decisions remain with credit professionals.
A more standardized preparation layer can help credit teams:
- Create a clearer baseline for review. Analysts and reviewers begin with financial information organized in a more consistent structure.
- Support more consistent credit review. Standardized financial structures give analysts a common reference point for evaluating borrower information and investigating differences that require additional attention.
- Reduce dependence on individual methods. Work can move between analysts and teams without relying as heavily on personal spreadsheet conventions.
- Keep expertise focused on judgment. Credit professionals can spend more time interpreting borrower performance, reviewing exceptions, and making lending recommendations.
FlashSpread standardizes more of the financial preparation leading up to credit analysis, while leaving interpretation and lending decisions to credit professionals.
Conclusion
Standardized financial spreading gives commercial lenders greater control over the preparation process without limiting the professional judgment required for sound credit decisions.
By establishing a more consistent foundation for review, institutions can reduce unnecessary process variation, improve oversight, and make financial preparation easier to manage as lending operations grow.
FlashSpread supports this approach by transforming borrower financial documents into standardized financial spreads, reducing repetitive preparation and giving credit teams a more consistent starting point for analysis.
How much of the variation in your credit process comes from the borrower and how much comes from the way the spread was prepared? See how FlashSpread helps create a more consistent foundation for credit review.