

Commercial lenders depend on borrower financial information to evaluate cash flow, leverage, repayment capacity, and overall risk.
The source financial statements themselves may be outside the lender’s control. But how that information is captured, classified, calculated, and prepared for analysis is not. Errors or inconsistencies introduced during financial spreading can change the picture an analyst ultimately evaluates.
That matters because the effects do not necessarily stop with one spread. The same prepared financial information may later support underwriting, credit memos, annual reviews, portfolio monitoring, and future borrower analysis.
Key Takeaways
- Data quality depends not only on source documents, but also on how financial information is captured and prepared for analysis.
- Classification, calculations, period alignment, and missing information can all affect the financial picture presented to analysts.
- Small preparation issues can influence working-capital analysis, cash flow, ratios, and year-over-year comparisons.
- Review remains essential, but stronger processes can reduce preventable inconsistencies before analysis begins.
- FlashSpread helps lenders prepare borrower financial information in a standardized format for credit review.
Where Data Quality Issues Enter Financial Spreading
Financial spreading involves more than transferring numbers from one document to another.
Borrower financials arrive in different formats, use different terminology, and may cover multiple entities or reporting periods. That information must be interpreted and organized before analysts can use it consistently.
Variation can enter during several parts of the preparation process:
- Capture: A value may be entered incorrectly or placed in the wrong field.
- Classification: Similar financial items may be categorized differently across borrowers or reporting periods.
- Calculations: Totals, adjustments, or formulas may be applied inconsistently.
- Period alignment: Financial information may be associated with the wrong period or entity.
- Completeness: Information required for analysis may be missing or overlooked.
These issues do not necessarily mean the borrower’s source financial statements are inaccurate. They reflect the risk of introducing differences as source information is transformed into a format used for credit analysis.
That distinction is important.
Lenders may not control the quality of the documents they receive, but they can improve the consistency of how that information is prepared once it enters the credit process.
Small Preparation Issues Can Have Real Lending Consequences
A preparation issue does not need to be large to affect how an analyst interprets a borrower.
For example, a current liability classified incorrectly can affect working-capital analysis. An adjustment applied inconsistently from one period to another can change the way cash flow appears. A missing value may affect a ratio or make year-over-year performance appear different from the underlying borrower results.
The individual number may be only one part of the spread, but credit analysis relies on relationships between numbers.
Analysts use those relationships to identify trends, evaluate repayment capacity, understand leverage, and investigate changes in borrower performance. If the underlying inputs have been prepared inconsistently, additional work may be required simply to determine whether an apparent change reflects the borrower or the preparation process.
This is where data preparation begins to affect the reliability of credit analysis.
The stronger the inputs going into analysis, the clearer the foundation analysts have for applying professional judgment.
Review Is Important, but It Should Not Carry the Entire Burden
Credit teams will always need to review financial information.
Analysts should validate important figures, investigate unusual results, and determine whether the financial picture makes sense in the context of the borrower. Human judgment remains essential.
But review is less effective when analysts must repeatedly reconstruct the information before they can evaluate it.
Some issues are obvious. A total that does not reconcile immediately deserves attention. Others are harder to spot. A line item may be classified differently from the previous year while the spread still appears mathematically correct.
Subscribe to BeSmartee 's Digital Mortgage Blog to receive:
- Mortgage Industry Insights
- Security & Compliance Updates
- Q&A's Featuring Mortgage & Technology Experts
Adding another layer of checking may catch some of those differences, but it does not address why they entered the process in the first place.
A stronger approach reduces preventable variation earlier, allowing analysts to focus their review on genuine exceptions, borrower-specific circumstances, and credit risk.
Building Greater Consistency Into Financial Preparation
Improving accuracy in financial spreading does not mean claiming every number will be perfect.
It means creating a more controlled and consistent process for moving information from source documents into analysis.
At an institutional level, lenders can strengthen that process by focusing on four practices:
- Define a consistent preparation approach. Establish clear expectations for how borrower financial information should be organized across deals and reporting periods.
- Establish source-reference practices. Give analysts a clear process for checking prepared values against supporting borrower documents when needed.
- Create earlier review checkpoints. Build processes for identifying missing, unusual, or inconsistent information before it reaches deeper stages of credit review.
- Preserve analyst judgment. Keep experienced credit professionals focused on interpreting borrower-specific circumstances, exceptions, and risk.
These are process controls that can help lenders improve consistency while recognizing an important limitation: the quality and completeness of the borrower’s original source information still requires review.
The objective is not to replace verification. It is to give analysts a cleaner, more consistent starting point for that verification.
Improving Financial Preparation With FlashSpread
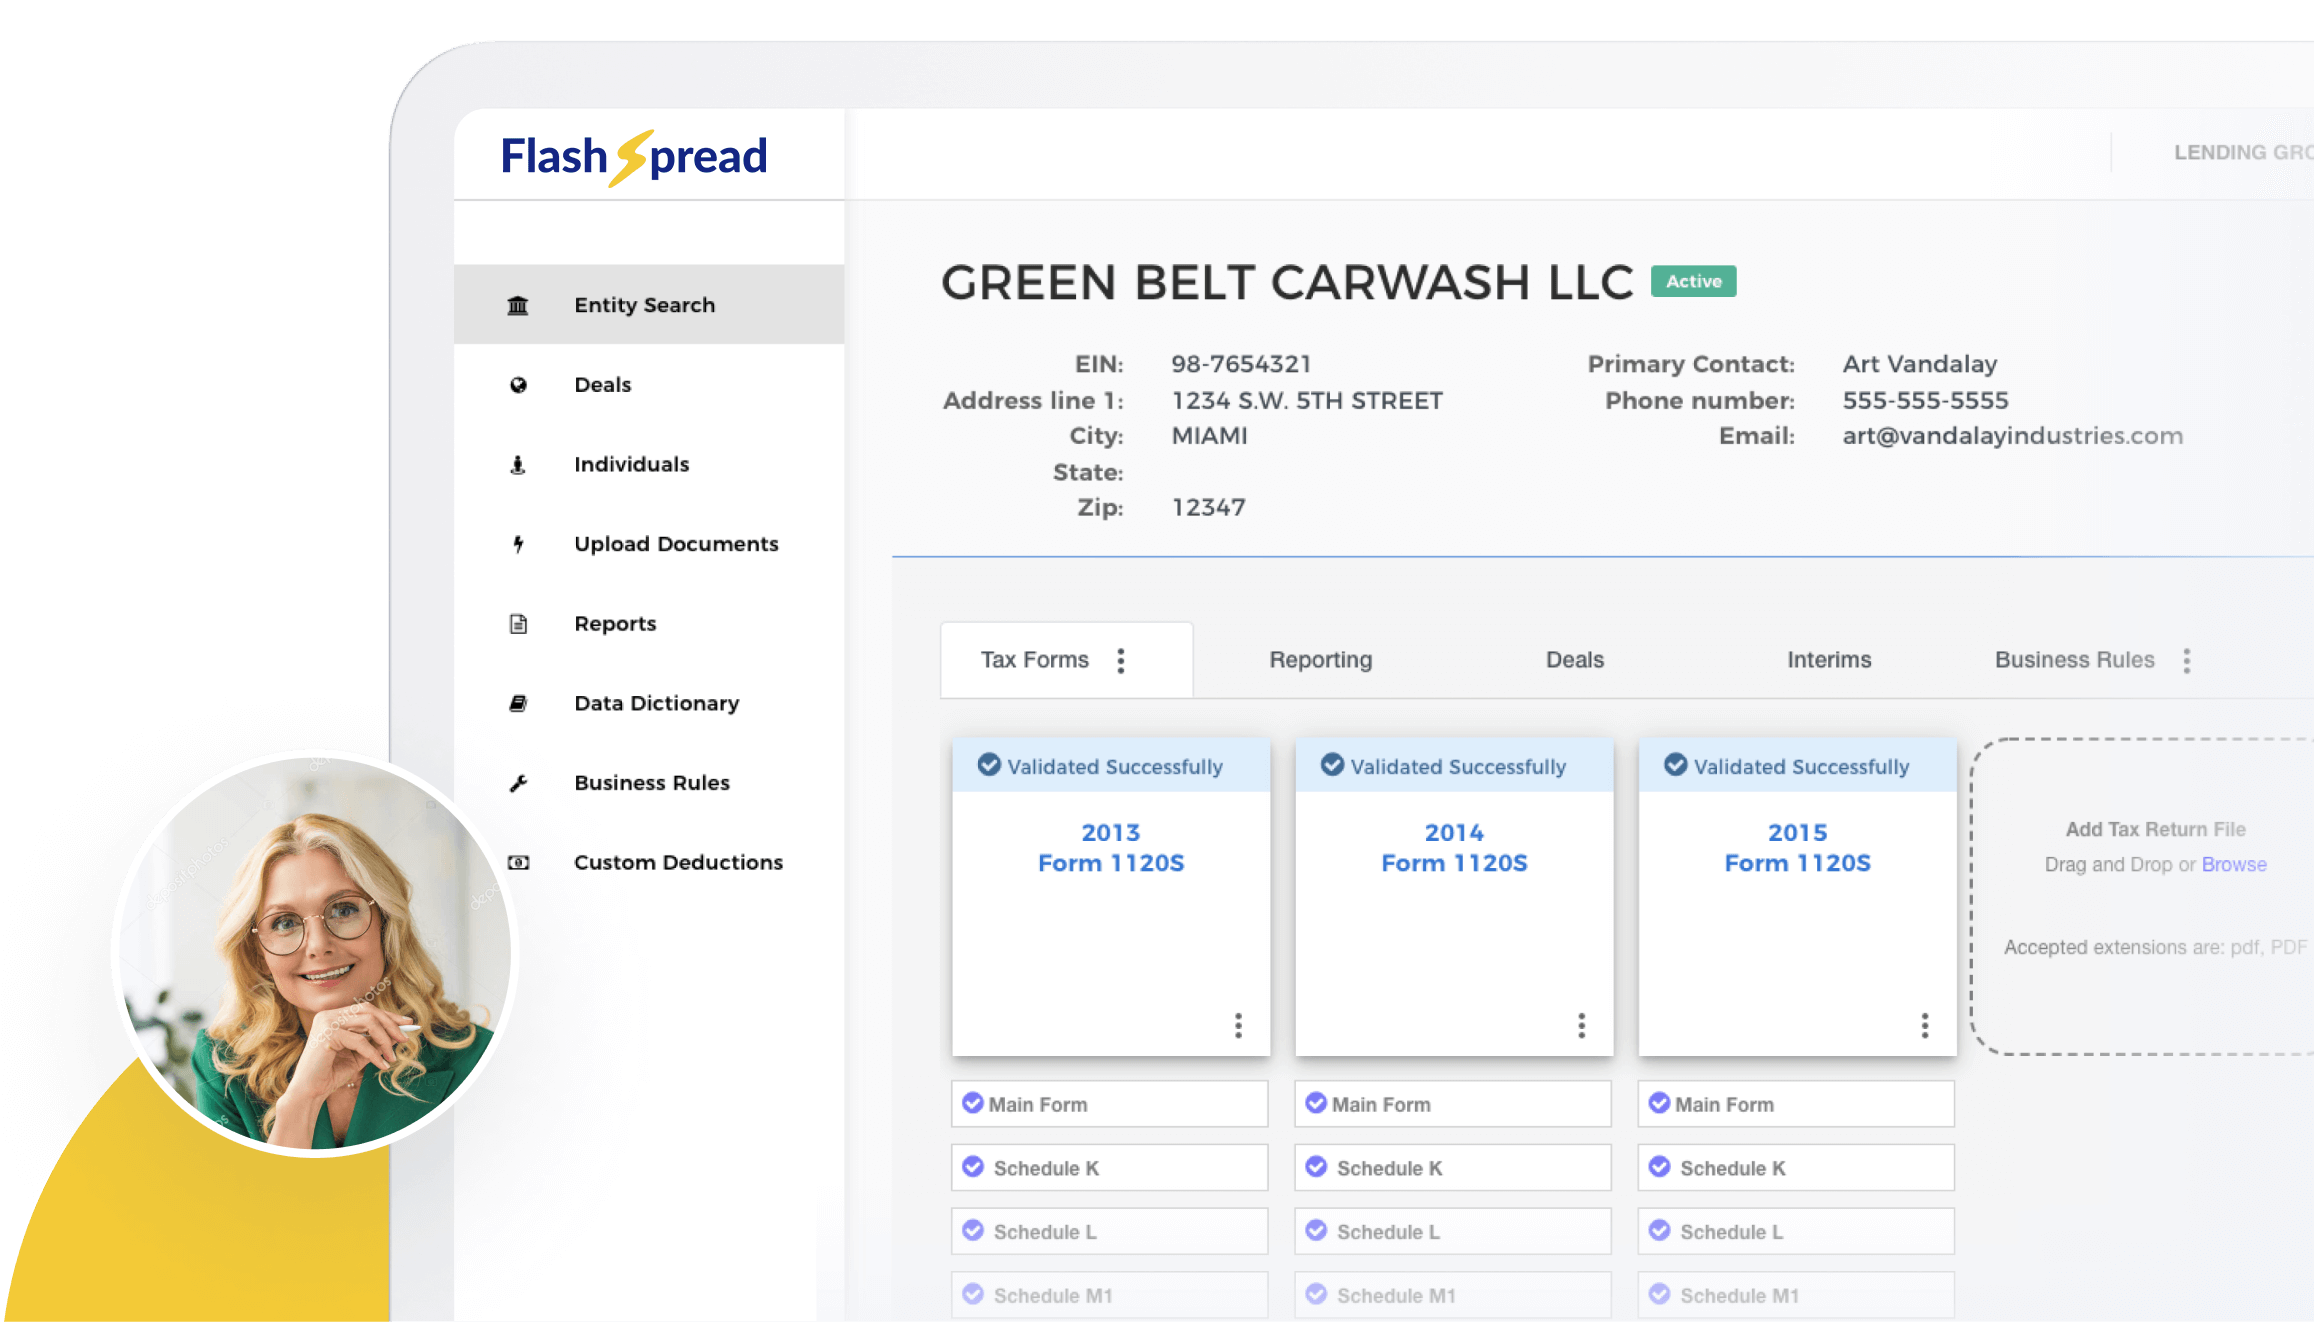
FlashSpread helps commercial lenders automate financial spreading and prepare borrower financial information for credit analysis.
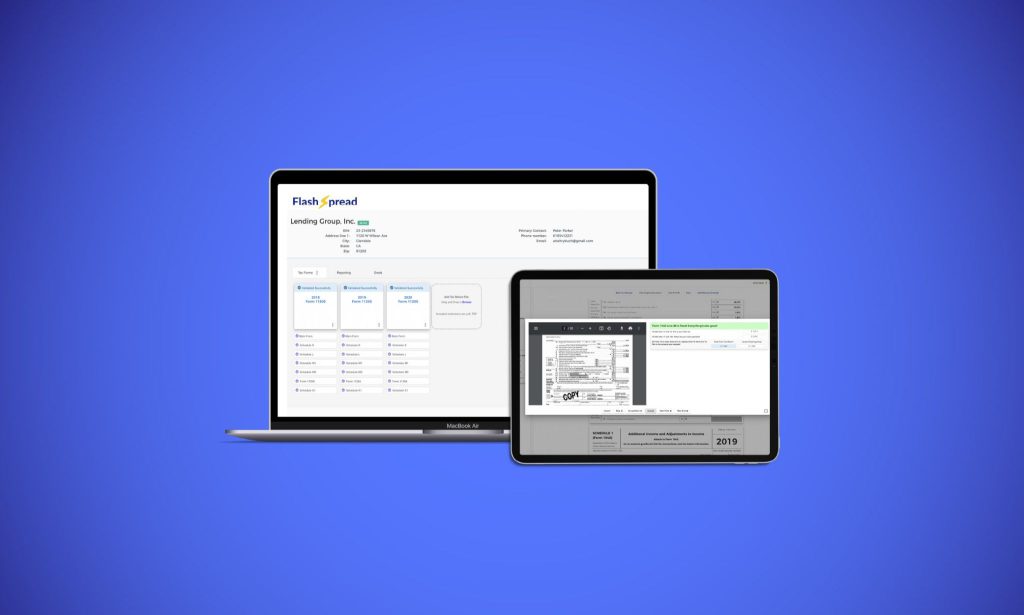
Using OCR and machine learning, FlashSpread extracts financial information from borrower documents and organizes it into standardized financial spreads for review.
With FlashSpread, lenders can:
- Extract financial information from borrower documents
- Organize that information into standardized financial spreads
- Reduce repetitive manual preparation and rekeying
- Give analysts a more consistent format for reviewing prepared financial information
- Move borrower financials toward analysis faster
The purpose is not to verify whether the borrower’s underlying source documents are accurate or to replace analyst judgment. FlashSpread helps reduce the manual preparation required to turn those documents into financial information ready for review.
That distinction matters because stronger financial preparation gives credit professionals a more consistent foundation for evaluating borrower performance, investigating exceptions, and making lending recommendations.
Conclusion
Credit decisions depend on more than the financial documents a borrower provides. They also depend on how that information is transformed into something analysts can evaluate.
A misclassification can affect working-capital analysis. An inconsistent adjustment can change the presentation of cash flow. Missing information can alter ratios or complicate comparisons across reporting periods.
These are not simply preparation issues. They can influence the financial picture used throughout the credit process.
Improving data quality therefore starts with creating a more consistent and controlled path from source documents to credit analysis, while preserving analyst verification and professional judgment.
FlashSpread helps commercial lenders transform borrower documents into standardized financial data faster, giving credit teams a more consistent starting point for analysis.
How consistent is the financial information entering your credit process? See how FlashSpread helps lenders move from borrower documents to standardized financial data prepared for credit review.